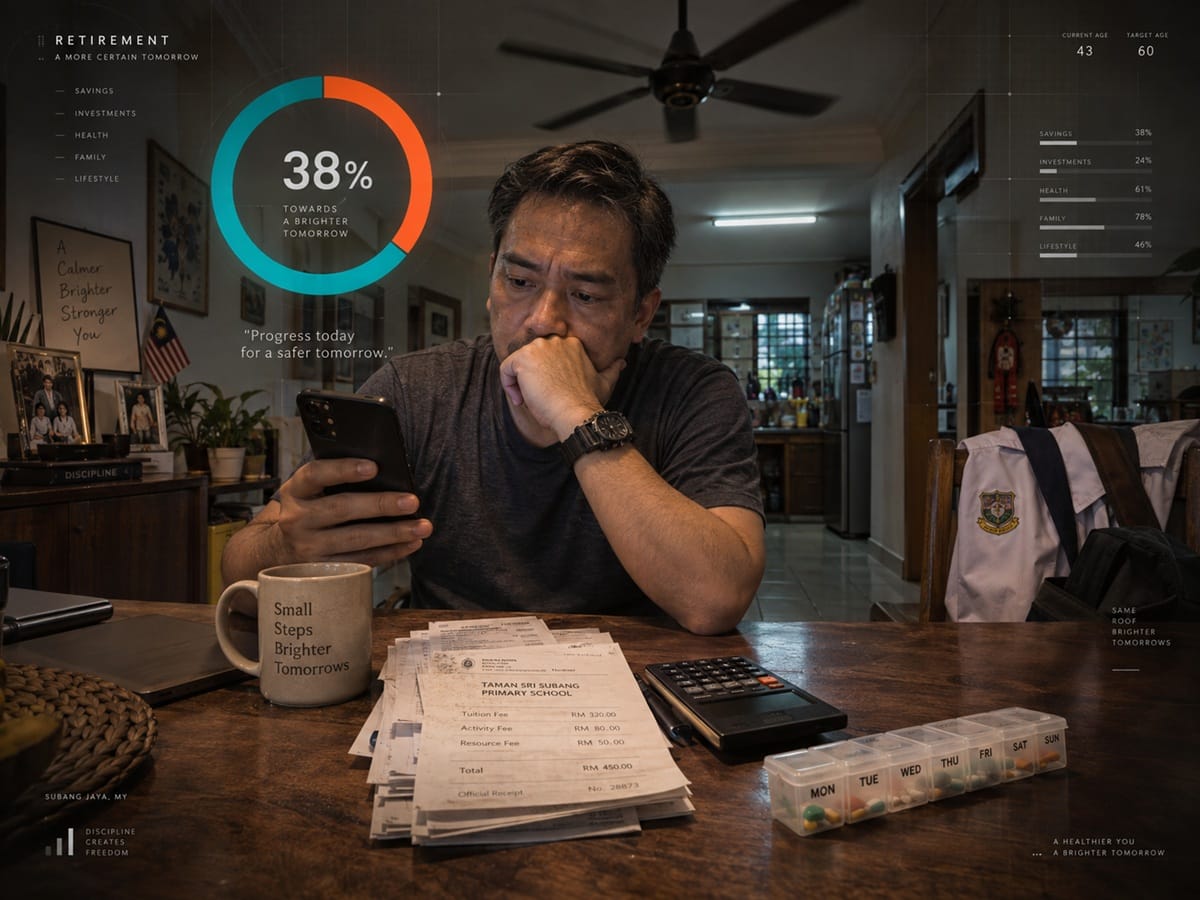
Out of every 100 EPF members, only 38 are where they should be.
That number comes from the latest update, and it deserves a slower read than the usual "savings are improving" headline. As of 31 May 2026, The Edge reported that 38.3% of active EPF members aged 18 to 60, about 3.04 million out of 7.94 million, had reached the Basic Savings benchmark for their age. A year earlier it was 35.0%. That is real progress, and it deserves some credit. But flip the coin over and you get roughly 4.9 million working Malaysians who are still behind. That is a lot of people.
First, what does "on target" even mean?
The benchmark is not one flat number for everybody. The EPF Retirement Income Adequacy Framework sets a target for every age from 18 to 60, building up to RM390,000 at 60. Along the way, you are meant to have RM15,900 at 25, RM107,000 at 40, and RM294,000 at 55.
Find your own age in the full table on that page and compare it with your latest EPF balance. I would rather you find out this week than at 54.
What RM390,000 actually gets you
This is the part that made me put my teh tarik down. Says worked out that RM390,000, spread over 20 years from age 60 to 80, comes to about RM1,625 a month. That is around RM54 a day for food, bills, medicine and everything else. Nasi lemak and teh tarik are fine at that budget. A hospital stay is another story.
Now put it next to EPF's own Belanjawanku guide, which puts a reasonable life for a single retiree at about RM2,690 a month. That leaves a gap of roughly RM1,065 every month, and this is for the people who hit the target. They are different yardsticks, so it is not a perfect comparison, and some of you will have other income later. Still, it is worth seeing the gap before you assume EPF will take care of everything. Also, 80 is not a fixed end date. If you live longer, the same money has to stretch further.
How so many of us ended up behind
It did not happen overnight. The Finance Ministry said Malaysians pulled out RM145 billion through four COVID-related withdrawal programmes by August 2022. Ministry figures show that the share of members under 55 with less than RM10,000 rose from 37% in April 2020 to 48% by September 2023, about 6.3 million people. Spread over 20 years, RM10,000 works out to less than RM42 a month.
Nobody should be shamed for that. In 2020, rent was due and rice does not buy itself. But this is the bill that has arrived, and it lands hardest on people in the middle of their careers.
The people I worry about most
That mid-career group is the one on my mind: kids in school, parents who need help, and a loan or two still running. RinggitPlus notes that the sandwich generation often pushes retirement savings and emergency funds to the bottom of the list, and I understand why. When school fees and a specialist appointment land in the same month, retirement feels like next year's problem.
It is next year's problem. It is also every year's problem. Compound growth works in both directions: it grows the money you put in, and it grows the gap when you put in nothing.
Start small, and take the free money
I am not a financial adviser, and your situation is your own. But if a friend asked where to start, I would say two things, and neither needs a big salary.
If you are self-employed or a gig worker, the i-Saraan scheme is the one to know. You put money in and the government adds 20% on top, up to RM500 a year and RM5,000 over your lifetime, until you turn 60. EPF's own example is RM2,500 in a year, which is about RM208 a month, for the full RM500. You can start with as little as RM1.
Here is what that could look like. Put in RM208 a month for ten years, which is how long the RM5,000 lifetime cap lasts at the full RM500 a year. Assume a 5% yearly dividend (EPF paid 6.15% for 2025, but it changes every year). After ten years you would have roughly RM37,700, against about RM31,400 without the match. Leave it alone for another ten years and it grows to around RM61,500. That is an illustration, not a promise. Still, a 20% top-up on day one is a head start that is hard to find anywhere else.
If you drive for an e-hailing or p-hailing platform, there is also i-Saraan Plus, which matches up to RM600 a year and RM6,000 over your lifetime when you contribute through your platform. You can only be in one of the two schemes. If you are on a payslip, EPF's i-Topup option lets you contribute above the statutory rate, though the 20% match is an i-Saraan perk.
Leave the flexible account alone
Each EPF contribution is split, and 10% goes into Akaun Fleksibel. RinggitPlus explains that you can withdraw from it anytime, from RM50, with no reason given, and approval usually comes within three working days. The same guide works out that taking RM5,000 out at a 6.15% dividend costs about RM308 a year in lost returns.
That convenience is the trap. One tap and the money is gone, and so is the growth it would have earned. Akaun Sejahtera, the 15% slice, can be used for housing, education and medical costs, and those are fair reasons. Just make every withdrawal a decision, not a reflex. A small emergency fund in an ordinary savings account means one bad month does not turn into a raid on your retirement.
The bottom line
The 38% is not a verdict. It is a starting line, and more people are crossing it every year. I would like you to be one of them, and I would like it to be on purpose. Look up your number for your age this week, put something small in, and think twice before you tap that withdraw button.
Figures and scheme details are from the sources linked above, as published up to September 2026. Check the KWSP website for the latest terms before you decide anything.
Kamarul Azwan (k.azwan@gmail.com) is a content creator under the Newswav Creator programme, where you get to express yourself, be a citizen journalist, and at the same time monetize your content & reach millions of users on Newswav. Log in to creator.newswav.com and become a Newswav Creator now!
The User Content (as defined on Newswav Terms of Use) above including the views expressed and media (pictures, videos, citations etc) were submitted & posted by the author. Newswav is solely an aggregation platform that hosts the User Content. If you have any questions about the content, copyright or other issues of the work, please contact creator@newswav.com.