
Payment reliability is becoming increasingly important for Malaysian retailers as businesses prepare for the year-end shopping rush, with 97% reporting payment performance issues over the past 12 months, according to the Adyen Retail Index 2026.
The findings come ahead of major shopping campaigns, including 11.11, 12.12, festive promotions and year-end clearance sales, when retailers typically experience higher transaction volumes across online and physical stores.
In a commentary by Soon Yean Lee, Country Manager, Malaysia, at Adyen, the payments technology company highlighted how transaction failures, checkout interruptions and fraud risks can affect businesses during periods of increased consumer spending.
The report also found that 59% of Malaysian consumers said payment errors negatively affected their perception of a business, while 26% had abandoned purchases because of security or trust concerns.
With retail spending expected to intensify during the final months of 2026, the commentary emphasised the need for reliable payment infrastructure, efficient checkout processes and fraud prevention measures that do not create unnecessary difficulties for legitimate customers.
 |
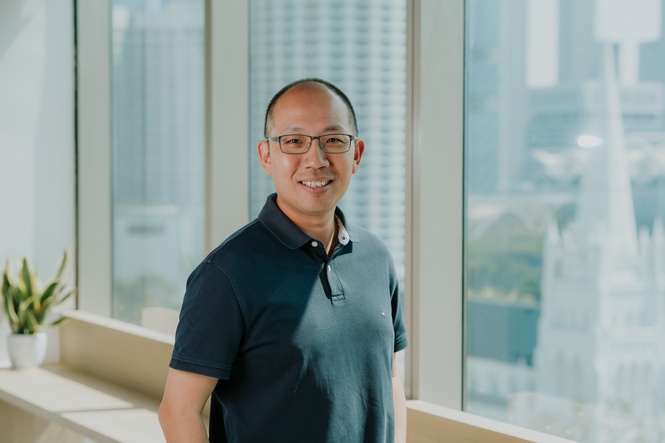
| Soon Yean Lee, Country Manager, Malaysia, at Adyen, highlights the importance of payment reliability, secure authentication and fraud prevention ahead of major year-end shopping campaigns. Photo: Adyen. |
Adyen Survey Finds 97% of Malaysian Retailers Experienced Payment Issues
Major shopping campaigns can create significant pressure on payment infrastructure as customers attempt to complete transactions within a relatively short period.
According to the Adyen Retail Index 2026, 97% of Malaysian retailers reported being affected by payment performance issues during the preceding 12 months.
These issues included failed transactions, slow payment processing and interruptions during checkout, potentially affecting retailers' ability to complete sales.
During major promotional periods, even temporary payment disruptions can create difficulties for customers attempting to secure time-sensitive offers.
For online retailers, a failed transaction may result in shoppers abandoning their baskets. Physical retailers may experience longer queues or interruptions to purchases when payment terminals or processing systems encounter problems.
Soon Yean Lee highlighted the importance of reviewing payment systems before major campaigns rather than addressing weaknesses only after problems occur.
Retailers are encouraged to examine recurring transaction failures, assess whether their infrastructure can handle higher volumes and monitor payment performance to identify potential disruptions.
Real-time monitoring can also help businesses detect issues early and respond before they affect a larger number of customers.
Payment Failures Can Affect Customer Trust and Future Purchases
Payment disruptions do not necessarily end with the loss of a single transaction. They can also influence how customers perceive a retailer and whether they are willing to shop with the business again.
The Adyen Retail Index 2026 found that 59% of Malaysian consumers said payment errors negatively affected their perception of a business.
Another 26% reported abandoning purchases because of concerns involving payment security or trust.
These findings suggest that checkout reliability contributes to the overall shopping experience, particularly when customers have already spent time comparing products, assessing prices and deciding what to buy.
A shopper who encounters a payment error may attempt the transaction again, but others may choose to purchase from a competing retailer instead.
To reduce unnecessary checkout difficulties, businesses can review the number of steps required to complete a transaction, provide payment methods preferred by their customers and ensure payment processing remains consistent across online and physical channels.
The commentary also emphasised that reliable payments can support longer-term customer relationships by reducing friction at the final stage of a purchase.
Smarter Authentication Could Reduce Checkout Friction
Alongside transaction reliability, retailers must balance convenient checkout experiences with appropriate security measures.
Payment authentication helps verify that a transaction is being carried out by an authorised person. Conventional methods may include one-time passwords, verification prompts and redirects to banking applications.
Although these methods serve important security purposes, additional verification steps can interrupt checkout, particularly when customers are purchasing through mobile devices.
Newer authentication approaches increasingly incorporate biometrics and passkeys, allowing customers to verify their identity using methods such as facial recognition or fingerprint scanning where supported.
The Adyen commentary also highlighted authentication orchestration, an approach that adjusts verification requirements according to the characteristics and risk of individual transactions.
Instead of applying identical checks to every payment, businesses can consider contextual information to determine when additional verification may be necessary.
For example, a returning customer using a recognised device may qualify for a less disruptive authentication process, while an unusual transaction may require additional checks.
The objective is to reduce unnecessary steps for legitimate customers while retaining safeguards against unauthorised payments.
Further information about the approach is available in Adyen's explanation of authentication orchestration.
One example highlighted in the commentary is Adyen Uplift's Authenticate, which uses information about transaction characteristics, risk and available authentication methods to help determine the authentication process.
While such tools are intended to make checkout more efficient, their effectiveness depends on implementation, the payment environment and the applicable security requirements.
94% of Malaysian Retailers Report Payment Fraud Exposure
Fraud prevention is another important consideration during high-volume shopping periods.
According to the Adyen Retail Index 2026, 94% of Malaysian retailers reported being targeted by or falling victim to payment fraud during the preceding 12 months.
The survey identified several commonly reported challenges:
- Refund fraud: 44% of retailers reported this type of fraud-related challenge.
- Phishing scams: 43% reported exposure to phishing-related threats.
- Chargeback abuse: 43% identified misuse of chargeback processes as a concern.
These figures indicate that payment fraud involves more than stolen card information or unauthorised purchases.
Businesses may also encounter attempts to exploit refund policies, manipulate transaction processes or misuse payment dispute mechanisms.
Such incidents can create additional financial losses and administrative work, particularly when retailers are already managing increased transaction volumes.
However, fraud controls that are overly restrictive can also cause legitimate transactions to be declined, creating difficulties for genuine customers.
Retailers therefore need to balance the identification of suspicious activities with the ability to process legitimate payments efficiently.
AI-Powered Fraud Prevention and Real-Time Transaction Monitoring
Artificial intelligence is increasingly being applied to payment fraud detection, allowing systems to analyse transaction patterns and identify potentially suspicious behaviour.
According to the Adyen commentary, AI-powered tools can help businesses assess transactions in real time, supporting the identification of fraud risks while reducing unnecessary payment declines.
This may involve analysing transaction characteristics and behavioural patterns to distinguish routine purchases from those requiring additional scrutiny.
For retailers, the intended benefit is to maintain payment security without creating avoidable obstacles for customers completing legitimate purchases.
However, automated fraud detection is not a guarantee against fraud, and businesses still need suitable operational processes, monitoring and procedures for handling disputed transactions.
The combination of real-time payment visibility and risk-based authentication can help retailers respond more effectively to the challenges associated with increased transaction activity.
Preparing Payment Systems for 11.11, 12.12 and Year-End Sales
The final months of 2026 include several major retail opportunities, from online shopping campaigns to festive promotions, year-end clearance events and spending associated with concerts, festivals and sporting activities.
For Malaysian businesses, preparing for these periods involves more than offering discounts or attracting customers through marketing campaigns.
Retailers also need payment systems capable of supporting higher transaction volumes while maintaining security and a convenient checkout process.
Based on the issues highlighted in the Adyen commentary, key areas for retailers to consider include:
- Payment system readiness: Reviewing infrastructure and addressing recurring transaction failures before major sales campaigns.
- Checkout experience: Reducing unnecessary steps and offering suitable payment options across online and physical stores.
- Transaction monitoring: Using real-time information to identify processing issues and respond promptly.
- Authentication: Applying appropriate security checks based on transaction risks rather than introducing unnecessary verification for every purchase.
- Fraud prevention: Monitoring suspicious activity while minimising unnecessary declines of legitimate payments.
The Adyen Retail Index 2026 findings indicate that payment performance, customer confidence and fraud prevention remain significant considerations for Malaysian retailers.
As businesses prepare for 11.11, 12.12 and the year-end shopping season, reliable and secure payment processing will be an important part of their ability to manage demand and complete customer transactions.