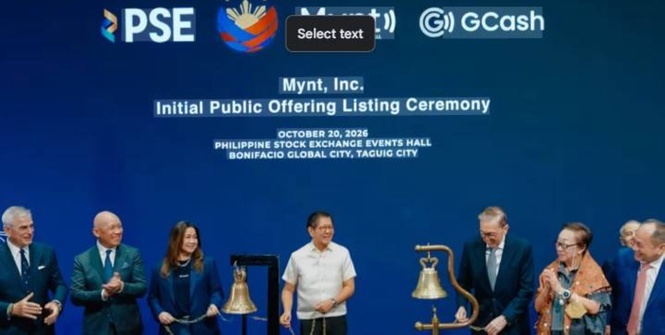
INVESTORS should turn their attention to Mynt Inc.’s third-quarter (Q3) earnings after the operator of e-wallet GCash made its Philippine Stock Exchange debut at its P6.60 offer price, analysts cautioned yesterday.
On its second trading day on Wednesday, Mynt shares dropped P0.01, or 0.15 percent, to close at P6.59 each.
Abacus Securities Corp. said Mynt’s unchanged closing price on its listing day suggested active price stabilization by the offering’s underwriters, although selling pressure appeared limited as total offer volumes remained below half of bid volumes during most of the session.
“Conversely, local buyers seemed willing to absorb whatever foreigners were selling. Then again this might be the stabilization fund, but our view is that there is evidence that the hype worked to some extent,” the brokerage said.
However, Abacus warned that expectations surrounding Mynt could raise the risk of disappointment when its third-quarter results are reported next month through parent Globe Telecom Inc. The brokerage noted that Mynt’s second-quarter performance had declined from the preceding quarter.
“For those who are looking to buy GCash, therefore, it is probably best to wait until Globe’s third quarter earnings release which will probably be in the second week of November,” Abacus said.
Despite the near-term uncertainty, COL Financial Inc. sees continued growth potential for Mynt, citing its market position, extensive user base and expanding financial services business as drivers of its earnings outlook.
The brokerage projects Mynt’s revenue to grow by 14.9 percent to P91.7 billion this year, before rising another 23.8 percent to P113.6 billion in 2027, supported by higher transaction volumes and the expansion of its CreditTech portfolio.
“Meanwhile, we expect net income to increase by 18.0 percent year on year to P20.4 billion in 2026 and 26.8 percent year on year to P25.8 billion in 2027,” COL Financial said.
The brokerage attributed Mynt’s growth prospects to GCash’s role in connecting Filipinos with digital financial services, with its extensive transaction data helping the company develop products tailored to customer needs.
COL Financial expects Mynt’s gross transaction value to reach P30.4 trillion by 2028, equivalent to a three-year compound annual growth rate of 21.3 percent from 2025.
Its credit business is also projected to expand, with the brokerage forecasting Mynt’s credit portfolio to reach P132.3 billion by 2028, representing a three-year compound annual growth rate of 40.2 percent from 2025. Its lending arm, Fuse, can leverage the GCash ecosystem to expand consumer lending, it said.
For Eric Jurado, hedge fund manager at SeA (Southeast Asia) Focus Portfolio, Mynt’s public listing should be viewed in the context of its longer-term business development rather than its initial stock performance.
“The IPO does not automatically make these services better. That remains Mynt’s responsibility. But the capital raised and the company’s transition to public ownership can support its next phase of growth, including product development and business expansion,” Jurado said.
“The ultimate measure of success for users will be whether Mynt continues to deliver useful, reliable services and expands access to financial opportunities,” he added.
Jurado said the listing also gives investors an opportunity to own a stake in a major Philippine fintech company and participate in the growth of the domestic corporate sector.
“The real questions are whether GCash can keep serving more customers, strengthen its competitive position, grow earnings per share and create lasting value for its owners. Today, the market gave GCash its first public price. From here, the business must build its long-term value,” he said.