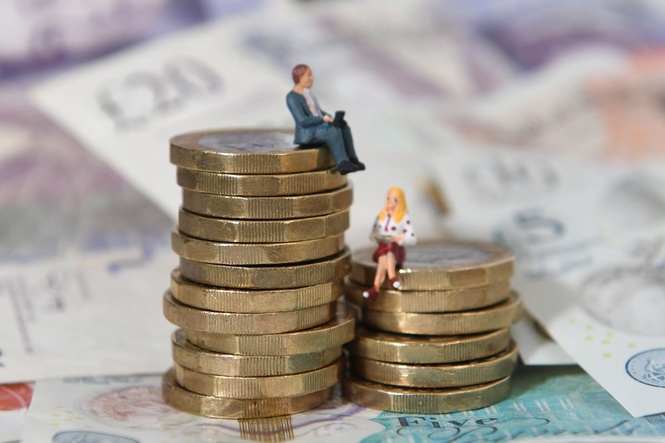
The gender pay gap is widely discussed, but less attention is given to the gender pension gap – the difference in retirement income between women and men.
While state pension incomes between men and women have become nearly identical, a large gender pension gap still exists when private and workplace pensions are included.
Research from the union Prospect found a 32.9% gender pension gap in the UK, a number which has been brought into the spotlight by charity Pregnant Then Screwed in its new Thanks for Your Service campaign.
Posters featuring “33% OFF” discount signs over images of women have been displayed on billboards and across social media this week as part of this campaign to highlight this pension gap.
“The reality is that, on average, women will retire with a pensions pot that’s 33% less than a man’s, which is a difference of £7,000 pounds per year,” says Rachel Grocott, CEO of Pregnant Then Screwed. “So, it’s not a small change issue. We’re talking about a life-changing amount of money.”
But what factors are driving this gender pension gap? And is there anything women can do about it?
What factors contribute to the gender pay pension gap?
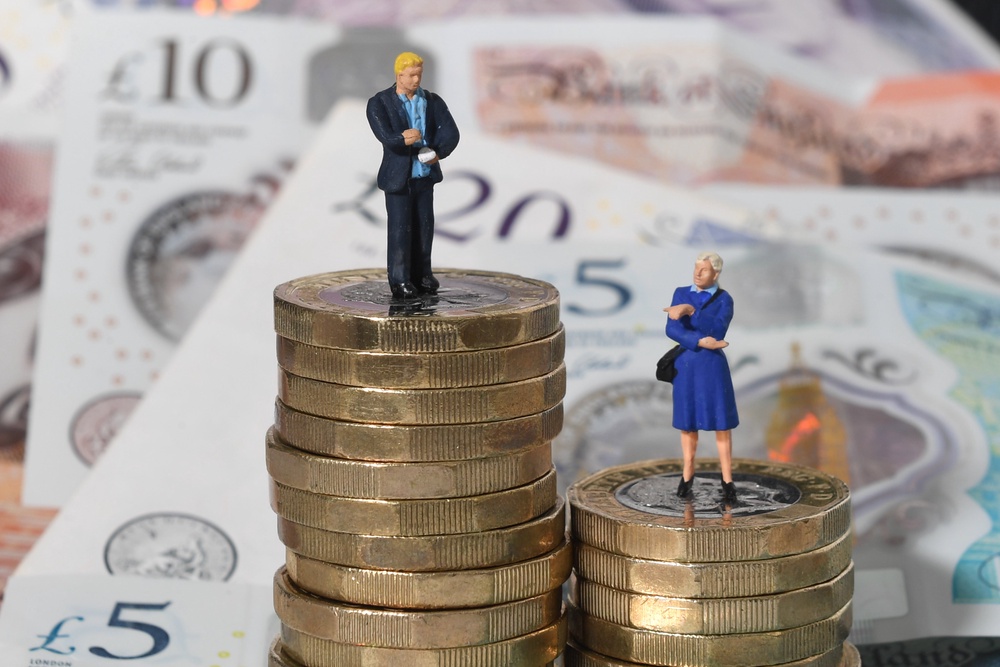
“There is a lot of pressure on women right now, which is why they often end up reducing their pension contributions, stopping them, or earn lower amounts of pension contributions because of the realities of the choices they make,” says Grocott.
Expensive childcare
The high cost of childcare is a significant factor contributing to the gender pension gap. Mums are more likely to reduce their working hours, take career breaks or make professional sacrifices to care for children which often affects their ability to save for retirement.
In a recent YouGov survey of 400 mothers, 42% said that they had little or no choice but to reduce their pension contributions due to childcare responsibilities.
Meanwhile, more than a third (36%) reported that they had reduced their working hours due to childcare, while 22% changed jobs to accommodate childcare. In addition, 18% said they had to prioritise childcare costs over pension savings.
“We have a ridiculously expensive childcare system, but we are seeing lots of return-to-office mandates and a high level of refusal of flexible working requests,” says Grocott.
Sandwich generation
Many women also find themselves part of the so-called “sandwich generation”, balancing the demands of raising children with caring for ageing parents or other older relatives.
“We often hear from women that as their children get older they begin to think about returning to the workforce or increasing their hours or going for a more senior role, but then suddenly they’re expected to care for older relatives, too,” says Grocott.
These caring responsibilities can create new obstacles, delaying these plans and further affecting their pension savings.
Despite these challenges, there are some practical steps women can take to plan for their financial future and better understand their pensions.
“We really want women to know that it’s not an individual failure; it’s a systemic failure and a societal failure. But, we also want them to feel empowered so that they can take action to change their immediate situation and to start having conversations about this,” says Grocott.
Here are some simple steps that mums can take…
Check pay slips during maternity leave
“One of the first things we encourage women to do is to check their pay slips during maternity leave,” recommends Grocott.
She explains that this is because women on maternity leave often get their pension contributions calculated incorrectly.
“Employer pension contributions should still be based on your standard salary, not on whatever your receiving for maternity. However, many women and companies aren’t aware of this,” says Grocott.
She recommends asking your HR department for clarity on how it has been calculated.
“We’ve heard from many women who have claimed that difference back and have campaigned for change in their organisations. So, this is a really important step to take,” says Grocott.
Have conversations with your partner and consider the options
“I think that this does need to be a conversation at a household level, especially given that disparity where men’s pensions tend to go up after having children, whereas women’s go down,” says Grocott.
“So, it’s important to look at the combined pension pots of both partners for the long term for the family, not just on an individual basis.”
Seeing if your partner is open to pitching in towards your pension could help balance your retirement savings.
“If a male partner can pay into a woman’s pension, that could be a beautiful fix,” says Grocott. “But this will only happen if there’s the awareness to drive the conversation in the first place.”
Don’t forget about pensions in divorce settlements
Divorce is another factor that affects men’s and women’s pension pots differently.
“Pensions are often not bought into divorce negotiations or settlements, and this really needs to be addressed,” says Grocott. “Women are often entitled to a portion of their partner’s pension in divorce settlements, but this often doesn’t happen.”
Legal and General’s website states that this can create some big problems for women, who are more likely to waive their rights to their partner’s pension during a divorce, despite entitlement to a share of their private pension wealth, and to see their annual income fall after the divorce, making it harder for them to save into their own pensions.
“So, it’s really important for couples to have these conversations and to think about if the relationship does end, what steps would they take to ensure fairness for both parties,” says Grocott.
Utilise free resources and advice
There is a vast range of free, reliable resources that offers practical advice, planning tools and support.
For example, MoneyHelper is a free, impartial, government-backed service providing guidance on planning for retirement, increasing state pension entitlement, understanding workplace pension contributions and protecting pension rights during divorce or separation.
Meanwhile, the Scottish Widows app offers a designated Women and Retirement Journey feature, which includes a career break modeller that helps women understand the long-term financial impact of time away from work and explore potential investment options.
The GOV.UK national insurance record checker also allows users to review their national insurance contributions, check their qualifying years towards the state pension and explore whether they may be eligible for national insurance credits linked to child benefit or caring responsibilities.
Remember that it’s never too late
It’s never too late to trace lost pensions pots or maximise employer matching in order to boost your pension pot.
“The message that it’s never too late is something we really do want to get across,” says Grocott. “It never is too late to check your pension, make changes and start these conversations.”
Read MoreThe six crucial finance questions every woman must ask before maternity leave
Motor finance compensation scheme set for legal challenge next February
Half a million UK workers to get pay boost worth over £1,000
Plans aim to help people with terminal illness unlock private pension
Expert explains what happens to your money if you die without a will
Solicitor shares the common mistakes people make when writing their wills