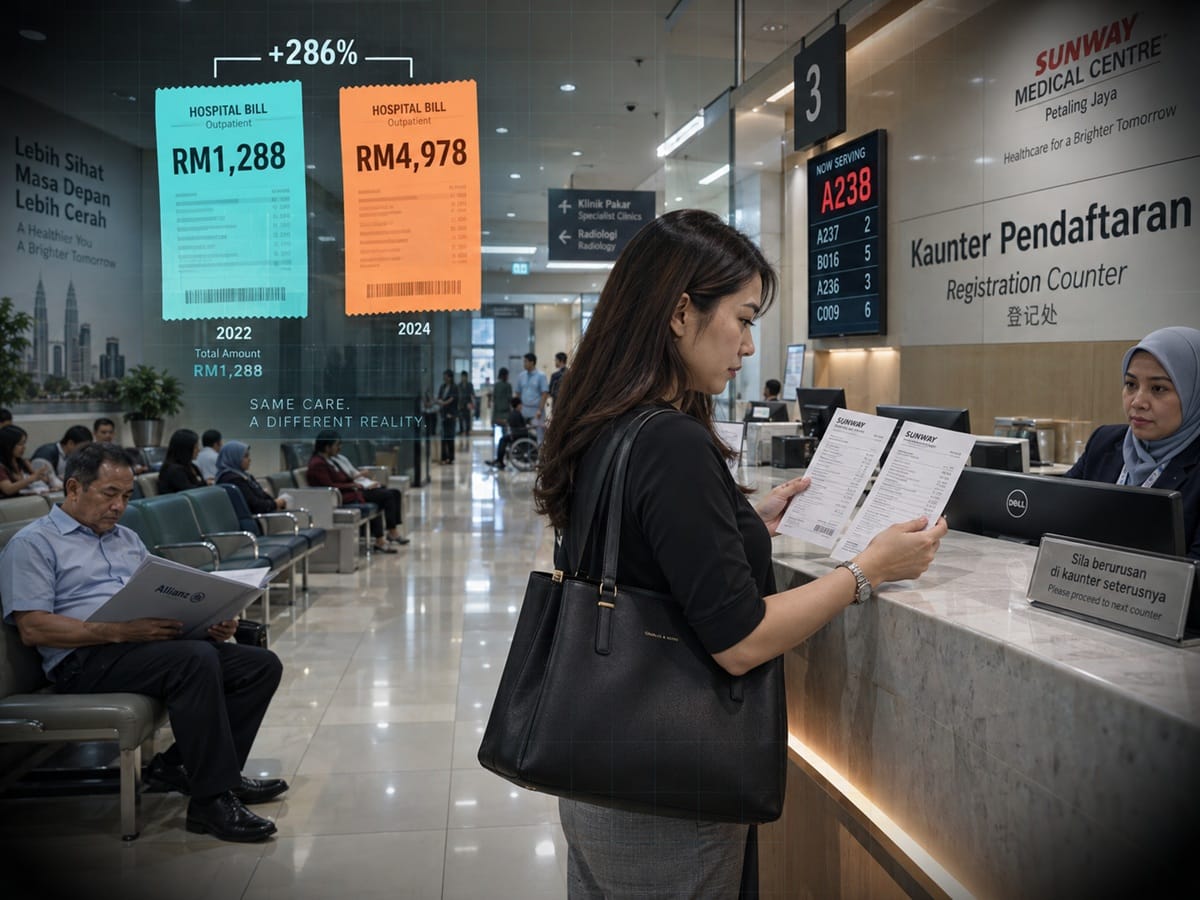
The same dengue treatment averaged RM3,690 more on a guarantee letter.
Same mosquito, same illness, different price tag. In a briefing to Parliament in December 2024, Bank Negara and the Finance Ministry showed that private hospitals charged dengue patients on a guarantee letter an average of RM4,978. Patients who paid first and claimed later were charged an average of RM1,288. For pneumonia, it was RM6,859 against RM2,654.
What is a guarantee letter, and why does the gap matter?
A guarantee letter, or GL, is the paperwork that lets the hospital bill your insurer directly, so you do not fork out a sen upfront. It feels like a perk, and in an emergency it is a huge relief. Pay-and-claim is the opposite: you settle the bill first and get reimbursed later.
The gap works out to 286% more for dengue and 158% more for pneumonia on a GL. The briefing did not spell out why, and described hospital charges as "different and non-transparent". Deputy Finance Minister Lim Hui Ying said much the same in February 2025, though without numbers.
I will be upfront: this makes me angry, and not because any single hospital has been proven guilty of anything. These are averages. But a RM3,690 gap for the same illness deserves an explanation, and "the insurer is paying" is not one.
Where that money ends up: your renewal letter
Higher claims costs do not vanish. They show up on your renewal letter. Bank Negara told Parliament that medical claims costs rose a cumulative 56% from 2021 to 2023, while premiums grew only 20%. The catch-up came in 2024: 61% of revised policies went up by as much as 20%, 30% rose by 21% to 40%, 5% by 41% to 60%, and 4% by more than 60%. The same briefing noted that hospital supplies and services make up 59% to 70% of private hospital bills.
To soften the blow, Bank Negara's interim measures had insurers spread increases over at least three years through the end of 2026, with at least 80% of policyholders expected to see yearly adjustments below 10%. Those measures run out at the end of this year, so what happens next is worth watching.
The people I worry about most
I worry most about families where a parent's premium goes up every birthday and a grown-up child ends up paying it. Older policyholders did get one small mercy: those aged 60 and above on a minimum plan got a one-year pause on inflation-related increases. One year is not a plan.
Work does not always come to the rescue either. A Malaysian Employers Federation survey of 231 companies found that 68% of employers expect medical insurance costs to rise significantly in 2026. The federation's president said more companies will move towards co-sharing. Translation: more of the bill may land on you.
MediAsas: a cheaper start, not a cure-all
Now for some good news. According to the Finance Ministry, the government-backed base plan called MediAsas is in a Klang Valley pilot until October 2026, with a nationwide rollout planned for January 2027. The target premium range is about RM60 to RM550 a month depending on your age. You can join before you turn 70, and cover runs to 85. Six insurers and takaful operators are taking part, including AIA, Allianz, Great Eastern and Etiqa.
Malay Mail's explainer lists a RM100,000 annual limit on the standard plan and RM300,000 on the Standard Plus version. You pay a RM500 deductible per illness (RM1,000 from age 61), and at hospitals outside the panel there is also a 20% co-payment capped at RM3,000.
Now the fine print. CodeBlue's explainer points out that MediAsas excludes pre-existing conditions, has waiting periods of 30 days (120 days for specified illnesses), and does not guarantee premiums, since Bank Negara lets insurers revise them with 30 days' notice. So it is a cheaper starting point, not a cure-all. If you are healthy and priced out, take a look. If you already have a health condition, read the exclusions before you get excited.
What to do before your next renewal
I am not an insurance adviser, so treat this as what I would tell a friend.
First, read your renewal letter, including the age band and the new premium, before you decide anything. Second, do not cancel until something else is in place. A new plan can come with exclusions and waiting periods, and the week you are uncovered is the week you will need it. Third, ask your insurer whether a same-price or cheaper option is available. Under Bank Negara's 2024 measures, insurers were told to offer alternative products at the same or lower premiums with no extra underwriting or switching cost, so it costs nothing to ask what is still on offer.
Fourth, for planned procedures, check the industry price guide before you agree to a quote. LIAM, PIAM and the Malaysian Takaful Association published it in early 2026 for 26 common procedures, based on insurance claims data, and it is a free PDF on their websites. In LIAM's price ranges, cataract surgery shows a typical bill of RM8,400, with a middle range of RM6,800 to RM10,300. Dengue and pneumonia are not in it, but a written estimate you can compare beats a number you only see on the way out.
Fifth, if you are priced out, look at MediAsas from January and compare its co-payments and exclusions with what you have now.
The bottom line
Nobody chose this. Not the family paying the premium, and not the parent whose plan climbs with every birthday. But cancelling is the one move that can turn a bad week into a ruinous one. Keep your cover, ask questions before you accept a bill, and be loud about wanting prices you can see. A RM3,690 gap for the same dengue should never be a surprise you only learn about in Parliament.
Figures and scheme details are from the sources linked above, as published up to September 2026. Check with your insurer for the latest terms before you decide anything.
Kamarul Azwan (k.azwan@gmail.com) is a content creator under the Newswav Creator programme, where you get to express yourself, be a citizen journalist, and at the same time monetize your content & reach millions of users on Newswav. Log in to creator.newswav.com and become a Newswav Creator now!
The User Content (as defined on Newswav Terms of Use) above including the views expressed and media (pictures, videos, citations etc) were submitted & posted by the author. Newswav is solely an aggregation platform that hosts the User Content. If you have any questions about the content, copyright or other issues of the work, please contact creator@newswav.com.