RM5.3 billion debt says 'sikit-sikit' isn't so sikit anymore.
One BNPL instalment on its own is nothing, that's exactly the trick. RM50 a month for a pair of shoes, RM80 a month for a new bag, whatever it is, it barely registers against your salary. I know because I've used it myself and, on its own, it was completely manageable. The problem only showed up later, when "just one" quietly became three, and three became a monthly total I hadn't actually sat down and added up until it was already due.
That's the trick of "bayar sikit-sikit" culture. Nothing about it feels like debt in the moment. It feels like convenience.
The RM50 a month lie we tell ourselves
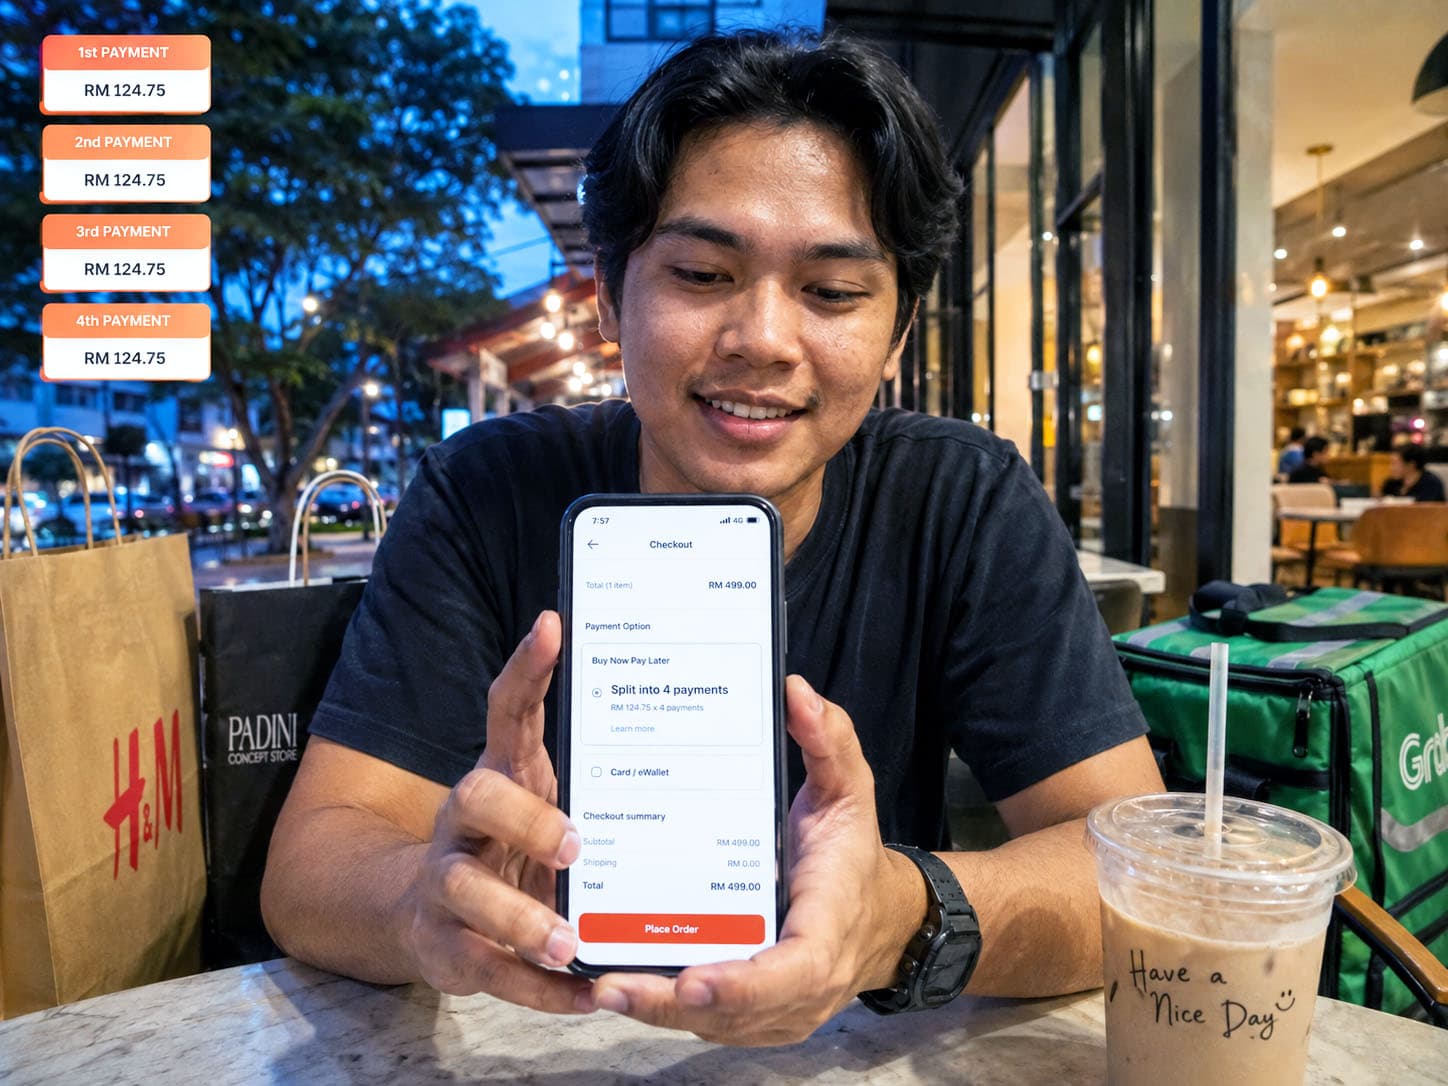
Here's the scenario that plays out constantly, and probably sounds familiar. You're scrolling, something catches your eye, and right there at checkout is a button offering to split it into four payments instead of one. The item might cost RM320. Framed as one payment, that number makes you pause. Framed as "RM80 a month," it barely registers as a decision at all. Your brain does the math on the smaller number, not the real one, and that's exactly the point. Splitting a price doesn't reduce what you owe, it just reduces how much it feels like you owe.
Now imagine that happening across three different apps in the same month. Atome for a fashion haul, Grab PayLater for a phone upgrade, a credit card EPP for a laptop. Each one, viewed alone, looks like a perfectly reasonable RM50 or RM80 monthly line item. Stack them together and you've quietly built yourself a second rent payment, except nobody sends you one consolidated bill reminding you of the total. You have to go looking for that number yourself, and most people never do until something forces the issue.
The numbers say this isn't a small trend anymore
This isn't just a feeling, the data backs it up. Malaysians collectively owe RM5.3 billion in BNPL debt as of the end of March 2026, up RM400 million in just three months, spread across 8 million active accounts. Around 40 percent of BNPL users in Malaysia are aged 30 or under, and most transactions are small, everyday purchases, food, groceries, transport, typically under RM100 each. That last part is what makes it sneaky. This isn't mostly people splitting payments on big-ticket items they genuinely couldn't otherwise afford. It's people splitting payments on things a normal monthly budget should already cover, which means the instalment habit isn't solving an affordability problem, it's just hiding one.
The concern from lawmakers isn't really about any single RM50 payment either. It's about how easy approval is compared to an actual loan. A bank loan comes with paperwork, checks, and a moment where someone asks whether you can actually afford this. Most BNPL checkout buttons ask for none of that. You tap once, and the commitment is made before you've had time to think it through the way you would with a formal application. Regulators have started catching up, with the Consumer Credit Act 2025 now requiring BNPL providers to get licensed, but the underlying behaviour, tapping "split into 4" without doing the maths first, isn't something regulation alone fixes.
Where it actually goes wrong
It's rarely the first BNPL plan that causes damage. That one usually gets paid off fine, on time, no drama, which is exactly why people trust the second one, and the third. The damage shows up in the stacking, when three or four "small" monthly instalments land in the same week your rent, your phone bill, and your groceries are also due, and suddenly a perfectly manageable salary has more claims on it than it has ringgit to cover them.
I've felt the difference directly. With one instalment running, life continues completely normally. The moment it multiplies to a few running at once across different apps, the picture changes, not because any single payment got bigger, but because the total finally exists somewhere other than your head, and it's usually larger than you assumed.
What I'd actually tell a younger friend about this
If you need to split it, you probably can't actually afford it yet. That's blunt, and it won't be popular, but it's the honest version of the advice. BNPL isn't inherently evil, used occasionally and deliberately for something you'd already budgeted for anyway, it's a fine tool. The trap is using it as a way to buy things your actual take-home pay says no to, then convincing yourself the smaller number at checkout means the real cost went down too. It didn't. It just moved further away from where you'd notice it.
Before you tap that split-payment button again, do the boring thing first. Add up every active instalment you're currently carrying, all of them, in one place, right now. If that total makes you flinch, that's not the app being unreasonable. That's your actual spending finally showing itself, RM50 at a time.
Kamarul Azwan (k.azwan@gmail.com) is a content creator under the Newswav Creator programme, where you get to express yourself, be a citizen journalist, and at the same time monetize your content & reach millions of users on Newswav. Log in to creator.newswav.com and become a Newswav Creator now!
The User Content (as defined on Newswav Terms of Use) above including the views expressed and media (pictures, videos, citations etc) were submitted & posted by the author. Newswav is solely an aggregation platform that hosts the User Content. If you have any questions about the content, copyright or other issues of the work, please contact creator@newswav.com.