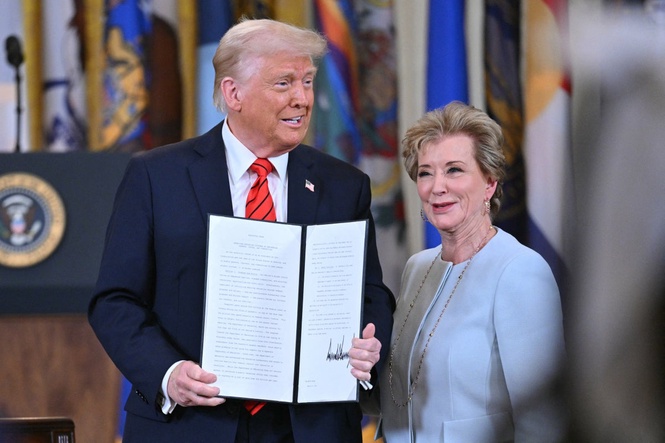
The Trump administration is preparing to resume wage garnishments for federal student loan borrowers in default after a six-year pause, according to reports.
It means that 9.3 million Americans who are at least 360 days late on payments, could see money taken from their paycheck before it hits their bank account, according to a Washington Sun report earlier this month.
The Department of Education has also decided to hire three debt collection agencies to help them, according to the report.
But there is some good news for borrowers, the Department of Education stated.
Federal student loan borrowers will have ample warning via an “offset” notice from the department, which explains that wage garnishment is imminent and sets a 65-day deadline for when garnishment begins. From that point, there are multiple options available to avoid the process.
Nixed in nine payments
This option allows borrowers to move their loans out of default if they can make nine consecutive monthly payments.
After the nine payments, the loan moves out of default. Borrowers must then opt into one of six repayment plans offered by the Department of Education. Typically, wage garnishment stops when a loan is out of default. However, borrowers can end wage garnishment by making five rehabilitation payments.
The first payment must be made within the borrower’s 65-day offset deadline.
Consolidation clean slate
Borrowers can combine all federal student loans into a direct consolidation loan that has a new interest rate and a single monthly payment, according to the Department of Education.
Because the consolidated loan is a new loan, it is not in default and essentially acts as a fresh start.
Consolidation must happen within 65 days of the borrower’s offset deadline.
Objection protection
A federal student loan borrower can file a wage garnishment objection in one of the following situations:
- The individual doesn’t owe the debt but is held responsible for owing a debt because of a mistake or oversight
- They aren’t behind on payments but are being held responsible for being behind because of a mistake or oversight
- They are in bankruptcy proceedings
- The individual is totally and permanently disabled because of “a physical and/or mental disability that severely limits your ability to work now and in the future,” the education department states.
The document needed to file the objection is included in the borrower’s offset notice, according to the Department of Education.
If the objection is approved, wage garnishment may be reduced or stopped, the department notes. If the objection is denied, wage garnishment will begin.
An objection must be filed within 65 days of the deadline noted in the borrower’s offset notice.
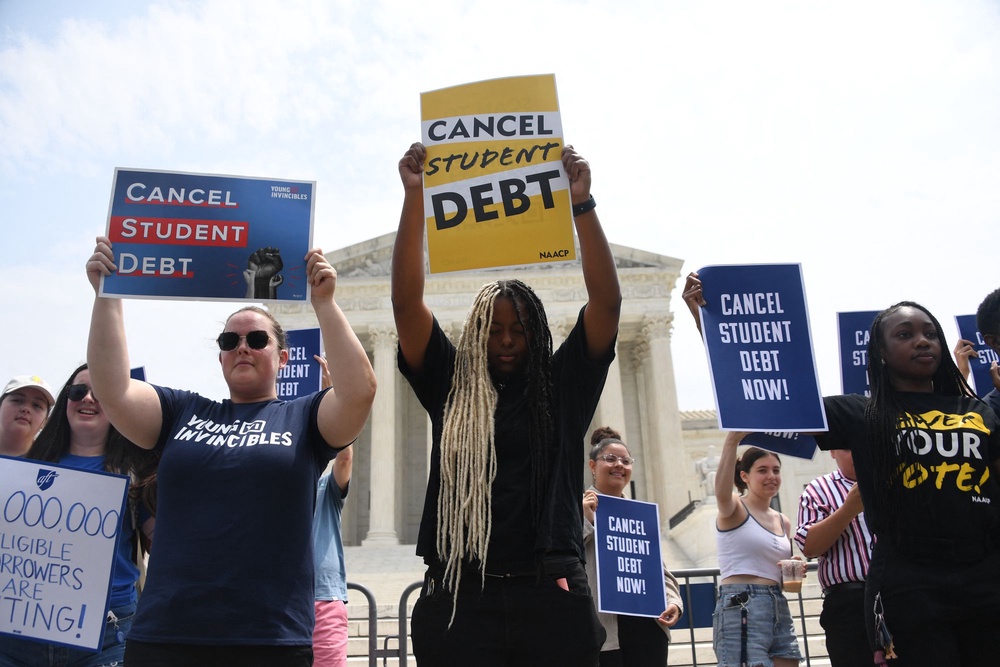
Discharge protection
Discharge is an option offered to borrowers in very specific situations, according to the Department of Education:
- Those who are totally and permanently disabled
- Those whose school closed while they were enrolled or within 180 days after they withdrew from the school
- Those who have qualified for loan forgiveness through the Public Service Loan Forgiveness program or certain income-driven repayment plans.
Borrowers have to apply for discharge, and discharge isn’t guaranteed.
Applications for discharge are available in the Department of Education’s form library.
Payment arrangement
The Department of Education offers a payment arrangement that lowers monthly payments so borrowers can make progress on repayment.
The arrangement will hold off wage garnishment as long as the first payment is made within 65 days of the borrower’s offset deadline, according to the department.
However, a payment arrangement won’t remove loans in default, the department notes.
Wage garnishment will stop if the borrower pays off their balance. Debit and prepaid cards are acceptable forms of payment, according to the Department of Education.
Read MoreGas prices under Trump eclipse highs of Biden era, federal data reveals
US workers paying a lot more for health insurance compared to last year, survey finds
US unemployment claims drop as experts warn it’s a ‘low-hire, low-fire’ landscape
US and Canada are both giving kids free money - but rules are very different
Banks are cancelling credit cards for money influencers who exploit rewards points
These grocery stores are rolling out a family-sized Thanksgiving meal for under $40