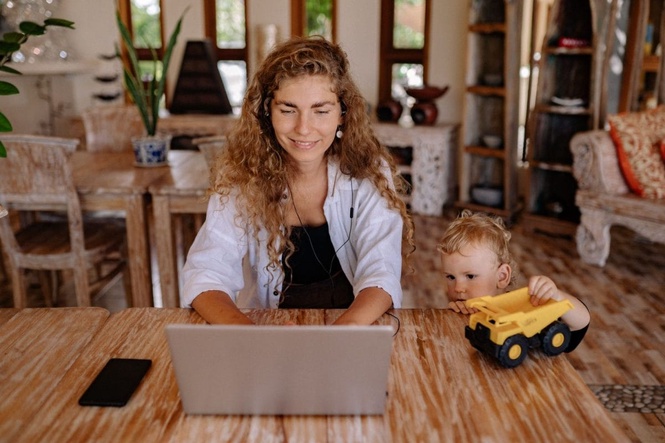
The paycheck you stop earning while raising children is only one part of the financial sacrifice.
A mother who steps away from a $60,000 job for several years might calculate the cost by multiplying her salary by the number of years she stays home. But that calculation misses retirement contributions, employer benefits, career advancement, and the potential effect on future Social Security payments.
Some of those losses can continue long after the children become adults.
Understanding the financial cost of a career break matters because caregiving decisions can influence a woman’s financial independence for decades.
Lost Salary Is Only the Beginning
Consider a woman earning $60,000 annually who leaves her job for five years to care for young children. Her forgone gross wages would total $300,000 if her salary otherwise remained unchanged. However, the actual household financial impact depends on taxes, childcare savings, transportation expenses, and other employment-related costs. A family that avoids $18,000 in annual childcare expenses may experience a smaller immediate cash-flow reduction than the salary figure suggests. The calculation becomes more complicated when accounting for raises, bonuses, and future career opportunities that might have occurred during those five years.
Retirement Contributions Stop Compounding
Leaving the workforce can interrupt contributions to a 401(k), 403(b), or other workplace retirement account. Suppose the employee previously contributed 6% of a $60,000 salary and received a 3% employer contribution, totaling $5,400 annually. Over five years, that represents $27,000 in missed retirement deposits before investment growth. If those contributions would have been invested and earned a hypothetical 6% annually, their future value could be substantially larger by retirement. This illustrates why the financial cost of a career break extends beyond money missing from the family’s checking account.
Social Security Can Reflect Years Without Earnings
Social Security retirement benefits are generally calculated using a worker’s highest 35 years of covered earnings. If someone has fewer than 35 years of covered earnings, zero-earning years can enter the calculation and lower the benefit. The Social Security Administration explains how lifetime earnings influence retirement payments. A woman who takes several years away from work may partially offset those years if she later accumulates 35 stronger earning years. However, someone with a shorter career or repeated caregiving interruptions may experience a lasting reduction in her own retirement benefit.
Career Progression Doesn’t Always Resume Where It Stopped
Returning to the workforce after several years can involve more than updating a résumé. Skills, technology, professional networks, and hiring expectations may change during an extended absence. Some returning workers accept lower-paying positions, reduced hours, or jobs outside their previous career paths. These decisions can affect future raises and retirement contributions even after employment resumes. The U.S. Department of Labor’s Women’s Bureau examines economic issues affecting women’s employment and financial security.
Employer Benefits Have Financial Value
A salary comparison doesn’t fully capture the compensation someone gives up when leaving a job. Employer-sponsored health insurance, disability coverage, retirement matching, paid leave, and other benefits can represent substantial economic value. A spouse’s employer may provide replacement health coverage, but premiums and deductibles could differ. Losing access to employer-provided disability insurance may also create additional household risk. Before leaving the workforce, families should calculate the value of benefits that will disappear or need to be replaced.
The Cost Can Become More Serious After Divorce
A long career interruption can leave one spouse financially dependent on the other’s income and retirement savings. If the marriage ends, the caregiving spouse may need to rebuild employment income while managing legal expenses and housing costs. Retirement account division, spousal support, and property rights depend on state law and individual circumstances. The financial impact may be particularly difficult for someone who has spent years outside the workforce. Maintaining personal savings, access to financial records, and awareness of marital assets can help protect long-term financial independence.
Families Can Reduce the Long-Term Damage
A career break doesn’t have to mean abandoning retirement planning altogether. Eligible married couples may be able to contribute to an IRA for a spouse with little or no earned income under the IRS’s spousal IRA rules. Families can also consider maintaining professional certifications, taking occasional contract assignments, or pursuing flexible employment when practical. These options aren’t equally accessible to every caregiver, especially when children require substantial support. Still, treating caregiving as a shared household investment can encourage both spouses to protect the caregiver’s financial future.
Caregiving Has Value Even When It Doesn’t Produce a Paycheck
The financial cost of a career break shouldn’t be interpreted as proof that staying home with children is a poor decision. Families make caregiving choices based on childcare availability, personal values, children’s needs, and financial circumstances. Unpaid caregiving provides real economic and personal value even though traditional retirement systems don’t always recognize it directly. The important step is calculating the long-term trade-offs before making assumptions about affordability. A family that benefits from one parent’s unpaid work should also consider how to protect that parent’s future financial security.
Did you take time away from your career to raise children, and did it affect your earnings or retirement savings later? Share your experience in the comments.
The post The Hidden Financial Cost of Taking Years Away From Work to Raise Children appeared first on Budget and the Bees.